
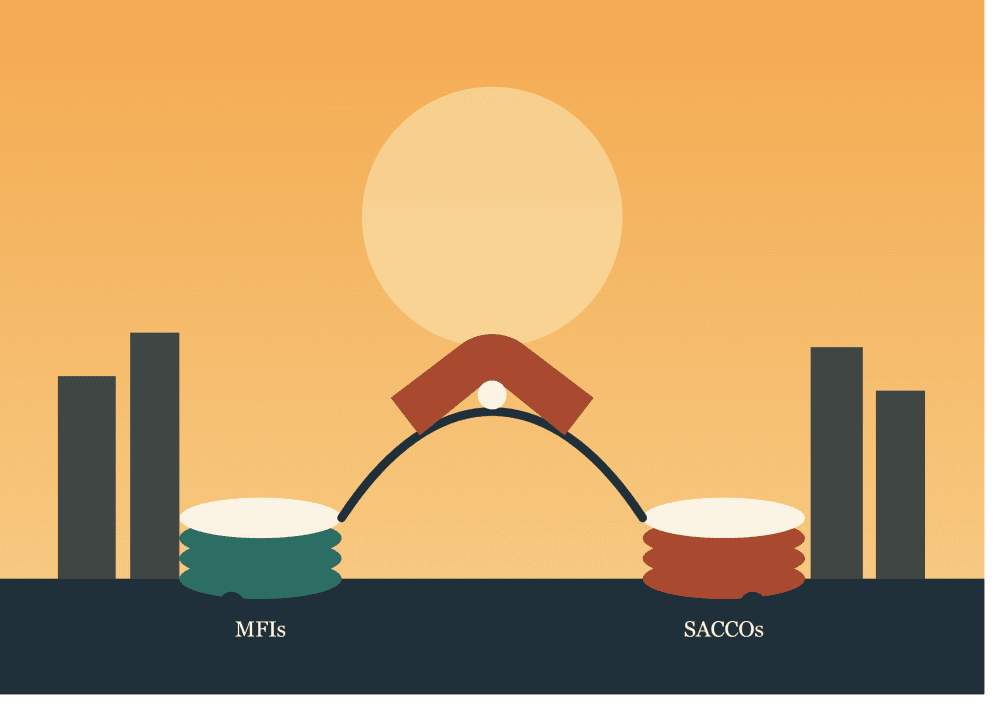
Partnerships, Not Competition
For decades, Microfinance Institutions (MFIs) and Savings and Credit Cooperative Societies (SACCOs) have been viewed as competitors pursuing the same customer. They often target salaried employees, small businesses, farmers, traders and entrepreneurs. Yet despite serving similar markets, both sectors continue to grapple with rising operating costs, customer acquisition challenges, increasing credit risk and mounting pressure from commercial banks and digital lenders.
Perhaps it is time to ask a different question.
What if the greatest opportunity for both sectors lies not in competing, but in collaborating?
The financial services landscape has changed dramatically. Customers no longer judge institutions based on whether they are SACCOs or MFIs. They simply want fast, affordable and reliable financial solutions. Institutions that insist on operating in silos risk becoming less relevant in an increasingly interconnected market.
Different Strengths, One Shared Mission
The reality is that MFIs and SACCOs possess complementary strengths.
SACCOs enjoy deep member loyalty, strong community trust and stable deposit mobilisation. Their cooperative model creates long-term relationships that commercial lenders often struggle to replicate.
MFIs, on the other hand, have invested heavily in credit appraisal, product innovation, technology, field operations and rapid loan processing. Their ability to design flexible financial products enables them to respond quickly to changing customer needs.
When these strengths are combined, both institutions become significantly stronger.
Instead of duplicating infrastructure, sales teams and operational investments, collaboration creates efficiencies while improving customer experience.
Partnership Creates Growth
A well-designed partnership model unlocks opportunities that neither institution can fully exploit alone.
A SACCO with a strong member base but limited lending capital can partner with an MFI to co-finance larger loans.
An MFI with nationwide products but limited community penetration can leverage SACCO networks to reach customers more efficiently.
Joint financial literacy programmes can educate members while creating demand for savings, insurance, business financing and investment products.
Rather than losing customers to commercial banks, digital lenders or fintechs, institutions retain them within a collaborative financial ecosystem.
Everyone wins.
Credit Quality
One of the greatest challenges facing financial institutions today is portfolio quality.
High default rates continue to erode profitability across the sector.
This presents another opportunity for partnership.
Shared credit information, joint borrower education, collaborative debt recovery initiatives and responsible lending practices can significantly reduce non-performing loans.
When institutions work together to promote financial discipline rather than simply chasing disbursement targets, the entire industry benefits.
Collections should not be viewed as a competitive function. Recovering distressed loans protects liquidity, safeguards member deposits and strengthens confidence across the financial system.
Technology Should Unite, Not Divide
Digital transformation no longer requires every institution to build everything independently.
Shared payment platforms, digital onboarding, data analytics, agency banking networks and API integrations allow multiple institutions to deliver seamless customer experiences while reducing costs.
Collaboration around technology also accelerates financial inclusion, particularly in rural and underserved communities where infrastructure investments remain expensive.
Instead of five institutions building five different solutions, partnerships can create one stronger ecosystem.
Financial Literacy Is the Missing Link
Many borrowers do not default because they lack income.
They default because they lack financial management skills.
MFIs and SACCOs have an opportunity to reposition themselves as financial educators rather than simply lenders.
Joint financial literacy programmes covering budgeting, debt management, entrepreneurship, investment and responsible borrowing build financially healthier members who borrow wisely and repay consistently.
Financial education is not a corporate social responsibility activity.
It is one of the most effective risk management strategies available.
Regulators Should Encourage Collaboration
The regulatory environment should continue supporting innovation while encouraging responsible partnerships.
Structured collaborations can improve liquidity management, reduce systemic risk and expand financial inclusion without compromising governance or member protection.
Industry associations, cooperative unions and microfinance networks also have a role to play by creating platforms where institutions share best practices, jointly address emerging risks and develop common industry standards.
The Future Belongs to Ecosystems
The financial institutions that will dominate the next decade will not necessarily be the biggest.
They will be the ones that build the strongest ecosystems.
Customers increasingly expect integrated financial solutions including savings, credit, insurance, investments, payments and advisory services under one trusted relationship.
No single institution can deliver every solution effectively.
Strategic partnerships allow each organisation to focus on what it does best while benefiting from the strengths of others.
Competition has undoubtedly driven innovation over the years. However, collaboration has the potential to create even greater value for members, customers and the wider economy.
The future of financial inclusion in Kenya will not be built by SACCOs alone.
Nor will it be built by MFIs alone.
It will be built by institutions that recognise that sustainable growth is no longer about protecting market share. It is about expanding opportunity together.
Joseph Njuguna Maina
About the Author
Joseph Njuguna Maina is a commercial leader with over a decade of experience in banking and financial services, specializing in revenue growth, credit management, strategic partnerships, and financial inclusion. He is the Senior Commercial Manager at Edenbridge Capital Ltd and Founder of Collectr Group.