
Why Members Must Choose Between Financing Consumption and Financing Production
By Prof. Fredrick Onyango Ogola, Founder Kenya Token, Africa Digital Assets and MD Catholic Token Africa.
Kenya’s cooperative movement stands at an important economic crossroads. For decades, Savings and Credit Cooperative Organisations (SACCOs) have played a remarkable role in mobilising savings, extending affordable credit and improving the financial security of millions of households. Among teachers, Saccos have become particularly important institutions of economic solidarity, providing access to credit, housing finance, education financing and opportunities for wealth accumulation.
But the question facing the next generation of SACCO leadership is no longer simply how much members can save or how much they can borrow. It is whether Saccos can evolve into institutions that finance production, stimulate enterprise, create assets and build intergenerational wealth.
In other words, will teachers continue to operate Saccos of yesterday, improve the Saccos of today, or deliberately build the Saccos of tomorrow?
This is not merely a technological question. It is an economic, institutional and intellectual revolution.
From financing consumption to financing production
The traditional SACCO model has largely revolved around mobilising members’ savings and advancing loans against their expected future income. This model has served an important purpose. It has enabled teachers to acquire homes, educate their children, purchase vehicles and meet other household obligations.
However, a fundamental economic question must now be asked: how much of the capital mobilised by teachers’ Saccos is financing the creation of new productive capacity?
There is a critical distinction between borrowing to consume and borrowing to produce.
A teacher who borrows to purchase a depreciating asset or finance recurring consumption may improve immediate living conditions but could also increase future financial obligations. Conversely, a teacher who borrows to establish a school, acquire agricultural equipment, invest in a commercial property, build a rental enterprise or finance a viable business creates an income-generating asset capable of supporting future repayments.
The argument is not that consumption financing should disappear. Households will always require credit for legitimate personal and social needs. Rather, the balance must change.
Teachers’ Saccos must become productive Saccos.
Their lending models should increasingly identify opportunities where members’ borrowing creates cash flows, employment, enterprise development and assets. The SACCO should not merely ask whether a member qualifies for a loan. It should also ask what economic value that loan will create.
This is the thinking behind Solomonic Economics: capital must serve the wider community, and economic prosperity must not be measured exclusively by the accumulation of financial wealth at the top. It must be measured by how effectively resources are converted into opportunities for those who have historically remained outside productive capital ownership.
The cooperative movement is uniquely positioned to operationalise this philosophy because it already possesses something many financial institutions struggle to build: collective trust and organised domestic savings.
AI is not software to download. It is intelligence to digitise.
The second revolution is intellectual.
Many institutions approach artificial intelligence as another software application to purchase, install or download. This is a fundamental misunderstanding of the transformation taking place.
AI is not simply about automating administrative functions. It is about amplifying human intelligence, improving institutional memory, strengthening decision-making and unlocking knowledge that would otherwise remain inaccessible.
Teachers should understand this better than most professionals.
Their greatest economic asset is not necessarily their monthly salary. It is their accumulated knowledge, professional experience, analytical capability and ability to learn, interpret and transfer knowledge.
Knowledge has one of the highest potential returns on investment because, unlike physical inventory, it can be replicated, shared and applied across multiple economic activities at relatively little additional cost. It does not require warehouses, physical stock or the same working-capital commitments associated with conventional production.
A teacher’s knowledge of agriculture, mathematics, technology, education, business or science can become the foundation of an enterprise, consultancy, digital product or investment opportunity.
The challenge is to digitise this intelligence and make it economically productive.
The future is not AI running Saccos and teachers. It is teachers and their intelligence running AI for Saccos.
Artificial intelligence should help SACCO boards understand member behaviour, forecast liquidity, identify emerging credit risks, detect fraud, improve customer service and make better-informed investment decisions. It should not replace human judgement, professional accountability or institutional values.
A SACCO that merely downloads AI software without upgrading the intelligence of its leadership will simply automate yesterday’s thinking.
The real competitive advantage will belong to institutions that invest in learning, research, data literacy and continuous intellectual development.
The Copernican revolution: changing the centre of the SACCO universe
There is a useful lesson from the Copernican revolution.
For centuries, people viewed the universe through an earth-centred understanding. Copernicus challenged that assumption and fundamentally changed humanity’s understanding of its place in the universe.
Institutions also operate with assumptions that can become obsolete.
For many Saccos, the member’s salary has traditionally been the centre of the financial universe. The lending model revolves around salary deductions, guarantors, collateral and repayment capacity.
Tomorrow’s SACCO must change that perspective.
The centre should be the member’s total economic potential: knowledge, skills, assets, entrepreneurial capacity, investment opportunities and future income streams.
Instead of seeing teachers merely as salaried borrowers, Saccos must recognise them as potential producers, investors, innovators and owners of productive enterprises.
This is a Copernican shift in cooperative thinking.
It changes the question from how much credit can be advanced against a teacher’s salary to how much wealth can be created from a teacher’s economic potential.
Kenya Token: connecting collective savings to productive assets
This transformation requires more than a change in attitude. It requires appropriate financial infrastructure.
This is where Kenya Token introduces an important frontier for the cooperative economy.
Through real-world asset tokenisation, eligible assets such as commercial buildings, rental properties, equipment and properly structured projects can be digitally represented through defined legal and economic rights.
For Saccos, this creates an opportunity to move beyond holding land and buildings as passive balance-sheet items towards making eligible assets productive and financeable.
Imagine a teachers’ SACCO with substantial land holdings. Rather than allowing those assets to remain idle, the SACCO could undertake a feasibility assessment, establish the highest and best economic use, develop an appropriate legal investment structure and explore financing through properly regulated tokenisation arrangements.
Teachers could potentially participate in productive projects through transparent digital investment structures, subject to applicable laws, member approvals and investor protections.
Kenya Token is therefore not simply about introducing another digital currency. Its institutional proposition is to connect identifiable assets, enforceable rights, transparent records and productive capital.
Artificial intelligence can help identify investment opportunities, assess project risks, forecast cash flows and monitor performance. Tokenisation can provide infrastructure for representing defined rights and connecting eligible projects to capital.
Together, they create an opportunity to transform Saccos from traditional savings-and-credit institutions into community wealth platforms.
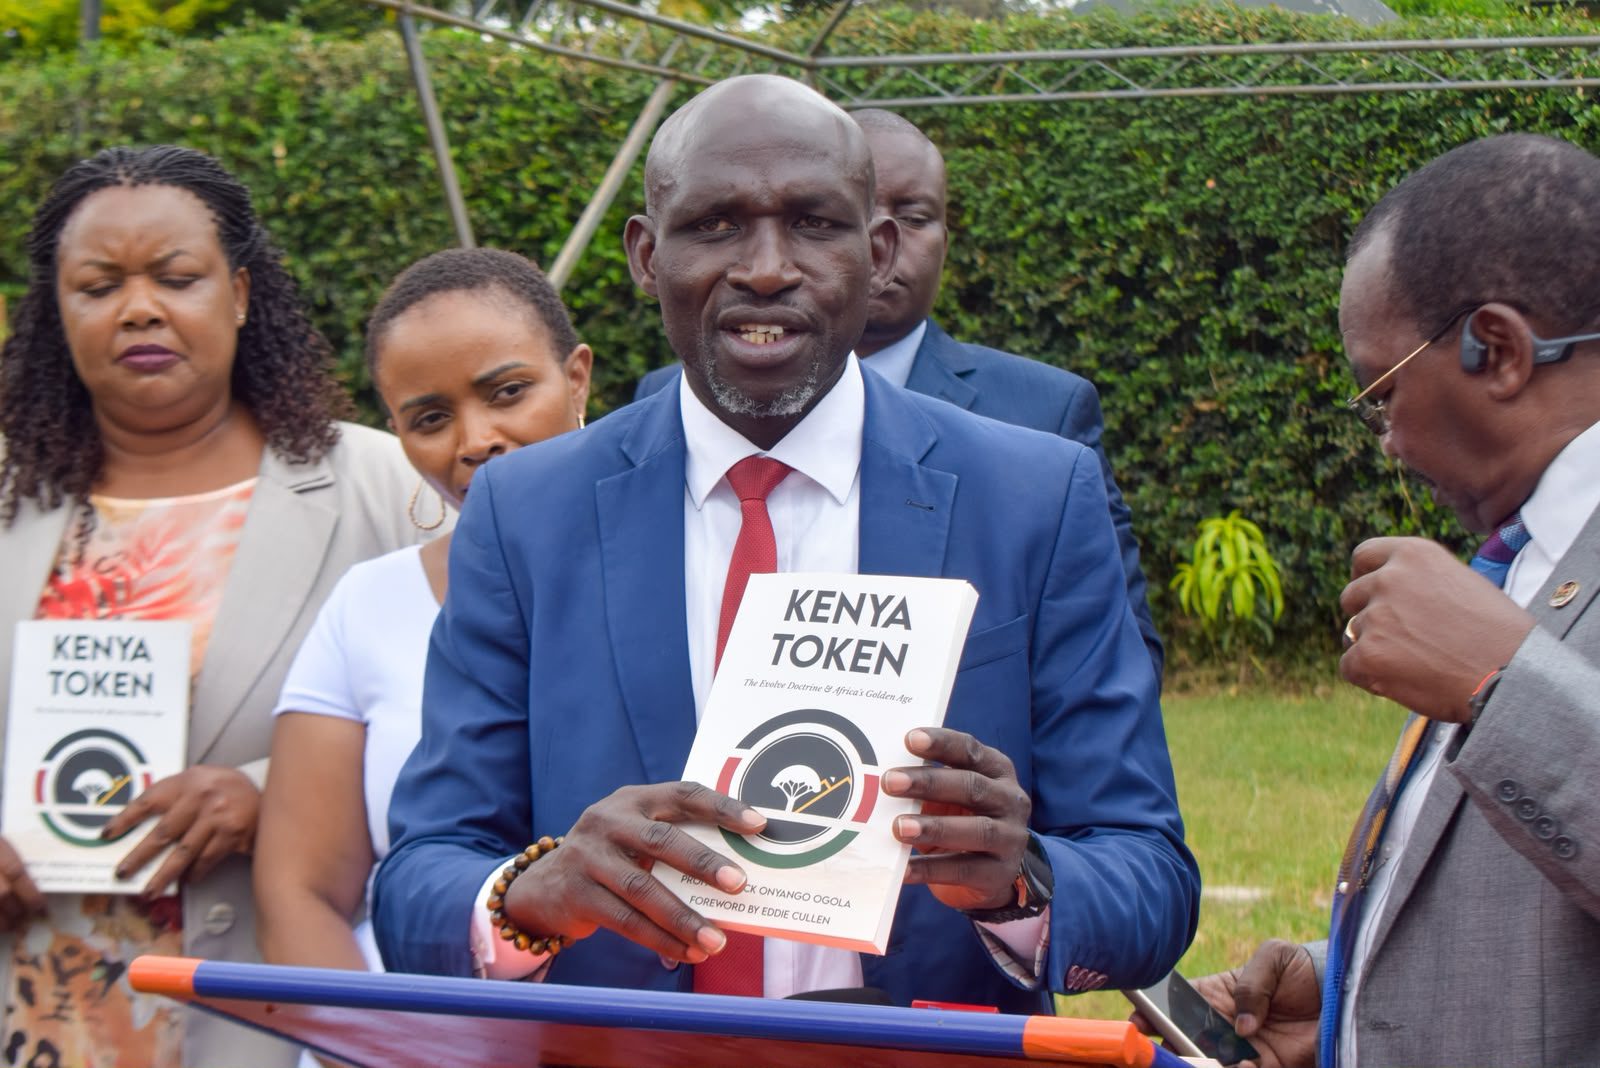
This is consistent with the broader thesis of my forthcoming book, Kenya Token, which explores how technology, institutional transparency and new financial architecture can democratise access to productive capital.
A token does not automatically confer land ownership, guarantee returns or eliminate regulatory obligations. Sound legal structures, due diligence, custody, disclosures and regulatory approvals remain essential.
Technology must serve institutional integrity, not become a substitute for it.
EVOLVE: the institutional philosophy for tomorrow’s SACCO
The transformation I am advocating is consistent with the EVOLVE Doctrine, which places governance, human capital, consequences for institutional misconduct, finance, infrastructure, social stability and technology at the centre of economic transformation.
For teachers’ Saccos, these principles have practical implications.
Governance must become meritocratic, data-driven and accountable. Leadership positions must be occupied by people with the competence to manage increasingly sophisticated financial institutions.
Human capital must become a strategic investment. Teachers must be empowered to acquire new skills in AI, digital finance, entrepreneurship, investment analysis and financial technology.
Capital allocation must become more productive. Saccos must deliberately identify opportunities to finance enterprises, productive infrastructure and income-generating assets.
Technology must improve transparency, operational efficiency and institutional accountability.
Above all, the cooperative movement must rediscover its original economic purpose: democratising ownership and enabling ordinary people to participate in wealth creation.
Solomonic Economics provides the moral and distributive dimension of this transformation. EVOLVE provides the institutional and governance framework. Kenya Token provides an emerging technological and financial infrastructure through which productive assets and capital can be connected.
These are complementary ideas, not competing propositions.
Growth requires crises: why Saccos must embrace disruption
There is another important reality that cooperative leaders must appreciate: growth is rarely achieved without confronting crises.
Institutions often interpret disruption as a threat to their survival. Yet crises can expose weaknesses, challenge comfortable assumptions and force organisations to discover capabilities they did not previously know they possessed.
A SACCO facing declining loan demand, rising competition, liquidity pressure, changing member demographics, technological disruption or increasing regulatory expectations should not automatically regard these developments as existential threats.
They should regard them as invitations to evolve.
The question is whether leadership will use these moments to rethink business models, improve governance, diversify income streams and strengthen institutional resilience.
The danger is not that Saccos will encounter crises. The danger is that they will continue applying yesterday’s solutions to tomorrow’s problems.
From crying to running: the developmental journey of a SACCO
The evolution of a SACCO can be understood through the developmental journey of a child.”
A child begins by crying, communicating basic needs and depending entirely on others. The child then learns to crawl, gradually developing coordination and independence. Eventually, the child walks, gains confidence and begins exploring the environment. With further development, the child runs, demonstrating strength, coordination, speed and confidence.
Institutions follow a similar developmental journey.
The SACCO of yesterday was largely dependent on physical branches, manual records, personal relationships and traditional lending practices. Like a child crying, it depended heavily on external structures and established routines.
The SACCO of today has learned to crawl and walk. It has embraced mobile banking, digital payments, automated accounting and faster lending processes. It has improved convenience and operational efficiency.
But the SACCO of tomorrow must learn to run.
It must anticipate rather than merely react. It must use predictive intelligence, personalise member services, finance productive assets, develop enterprise ecosystems and participate in the digital economy.
This developmental analogy should not be confused with Lawrence Kohlberg’s technical theory of moral development, which concerns the evolution of moral reasoning. However, the wider lesson of progressive development is relevant: institutions must continually mature in their capabilities, judgement and responsibilities.
The objective is not simply to become faster. It is to become more intelligent, productive and economically consequential.
The choice before teachers’ Saccos
The future of the cooperative movement will be determined by the choices its leaders make today.
Will teachers’ Saccos remain institutions where members save money, borrow against their salaries and repay through monthly deductions?
Will they become digitally efficient versions of the same traditional institutions?
Or will they become intelligent financial ecosystems that mobilise savings, digitise knowledge, finance production, unlock productive assets and build sustainable community wealth?
The opportunity is enormous.
Teachers are not merely employees who happen to save together. They are an organised community of knowledge workers with enormous intellectual and economic potential.
Their collective intelligence could become a source of innovation, entrepreneurship, investment and national development.
The next generation of SACCO leadership must therefore invest as much in the intellectual capital of its members as it does in financial capital.
My challenge to teachers is simple: stop thinking of yourselves primarily as borrowers. Start thinking of yourselves as producers, investors and owners.
And my challenge to SACCO boards is even more direct: do not spend the next decade digitising the past.
Build institutions that can finance the future.
Yesterday, Saccos mobilised savings. Today, they digitise money. Tomorrow, they must mobilise intelligence and productive assets to multiply wealth.
That is the journey from the SACCO of yesterday to the SACCO of tomorrow.
That is the EVOLVE imperative.